National Health Insurance Tax
National Health Insurance is a system of mutual assistance that protects health and livelihoods by having all members pay insurance taxes so that they can receive medical care without financial worries when they become ill or injured.
The financial resources of National Health Insurance consist of the insurance tax paid by all the insured persons and contribution from the national government. We provide medical expenses and various other benefits based on the financial resources. Therefore, the insurance tax you pay is an important source of funds for the national health insurance.
The financial resources of National Health Insurance consist of the insurance tax paid by all the insured persons and contribution from the national government. We provide medical expenses and various other benefits based on the financial resources. Therefore, the insurance tax you pay is an important source of funds for the national health insurance.
Table of Contents
1. Taxpayer
For National Health Insurance, the head of the household is the taxpayer. Therefore, notices and payments will be sent to the head of the household. Even if the head of household is enrolled in a health insurance other than the National Health Insurance, if any member of the family is enrolled in the National Health Insurance, the head of the household will be the taxpayer (fictitious household). However, in this case, the income of the householder is not included in the tax calculation. (When judging the reduction of insurance tax, the income of the householder is included in the calculation.)
Fictitious household
A fictitious household is a household in which the head of the household subscribes to the insurance of their workplace, such as as workplace health insurance or the workplace Medical Care System for the Advanced Elderly, and at least one other family member subscribes to National Health Insurance.
The head of this household will be the fictitious head of the household, and will be responsible for paying taxes on behalf of the household.
The head of this household will be the fictitious head of the household, and will be responsible for paying taxes on behalf of the household.
2. Payment Date
From June to January, there will be 8 payment dates.
| By period | Payment deadline | |
| Legal due date | 1st Term | June 25 |
|---|---|---|
| 2nd Term | July 25 | |
| 3rd Term | August 25 | |
| 4th Term | September 25 | |
| 5th Term | October 25 | |
| 6th Term | November 25 | |
| 7th Term | December 25 | |
| 8th Term | January 25 | |
| Rolling due date | 1st Term | February 25 |
| 2nd Term | March 25 | |
| 3rd Term | April 25 | |
- If the due date is a public holiday, the day following the public holiday will be considered the due date.
- Special collection from annuity is paid bi-monthly (April, June, August, October, December, February)
3. How to calculate tax amount
国民健康保険税は、「医療給付費」「後期高齢者支援金」「介護納付金」「子ども・子育て支援金」の4種類に分かれており、それぞれに種類ごとに、所得割額、均等割額、平等割額の3つの金額を合算したものが国民健康保険の税額になります。
| 令和8年度税率 | Overview | Medical Benefit contribution | Elderly support contribution | Nursing care contribution (only for those aged 40 to 64) | 子ども・子育て支援金 |
| Income-based | Calculated from the previous year's income 【Income - basic deduction (430,000 yen) x tax rate】 | 7.89% | 2.45% | 1.99% | 0.29% |
|---|---|---|---|---|---|
| Per capita-based | Calculated by the number of insured persons 【Number of insured persons x tax amount】 | 27,200円 | 9,000円 | 9,100円 | 1,100円 |
| Per household-based | Fixed amount per household | 26,800円 | 8,900 yen | 7,100 yen | 1,000 yen |
| Ceiling limit | Insurance tax limit | 670,000円 | 260,000 yen | 170,000 yen | 30,000 yen |
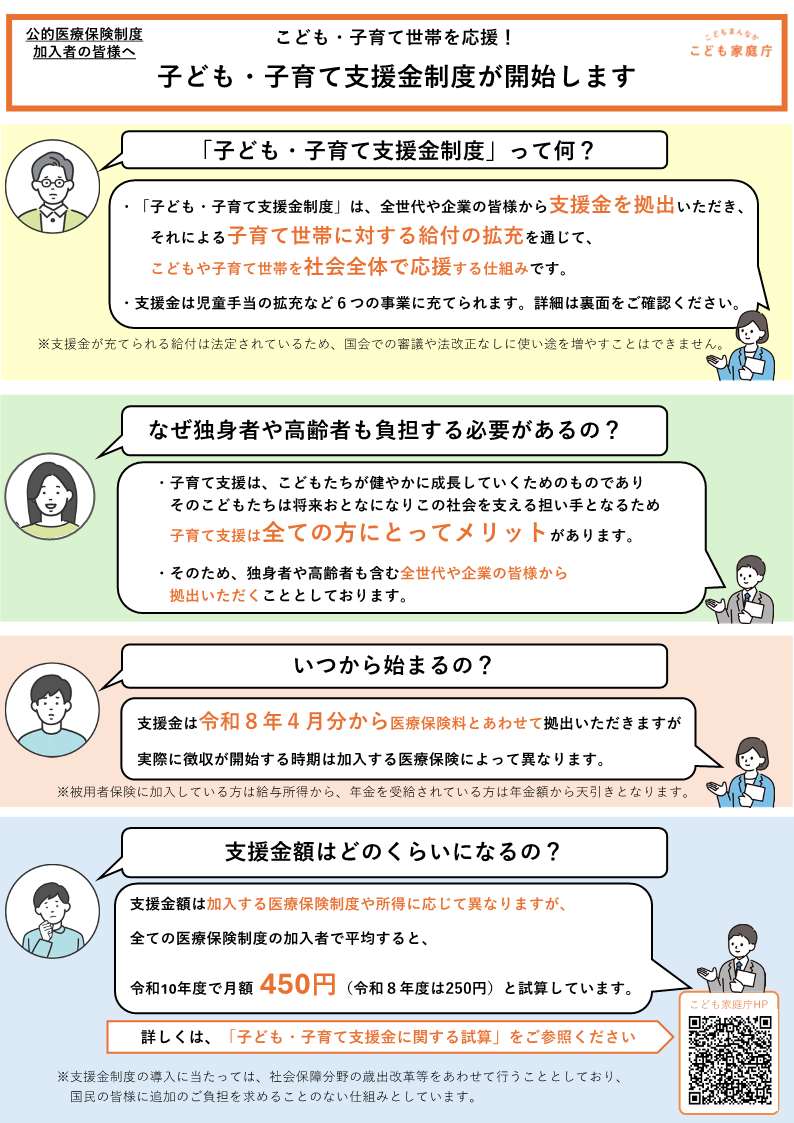
子ども・子育て支援金について
令和8年度(2026年度)から子ども・子育て支援金制度が創設されました。
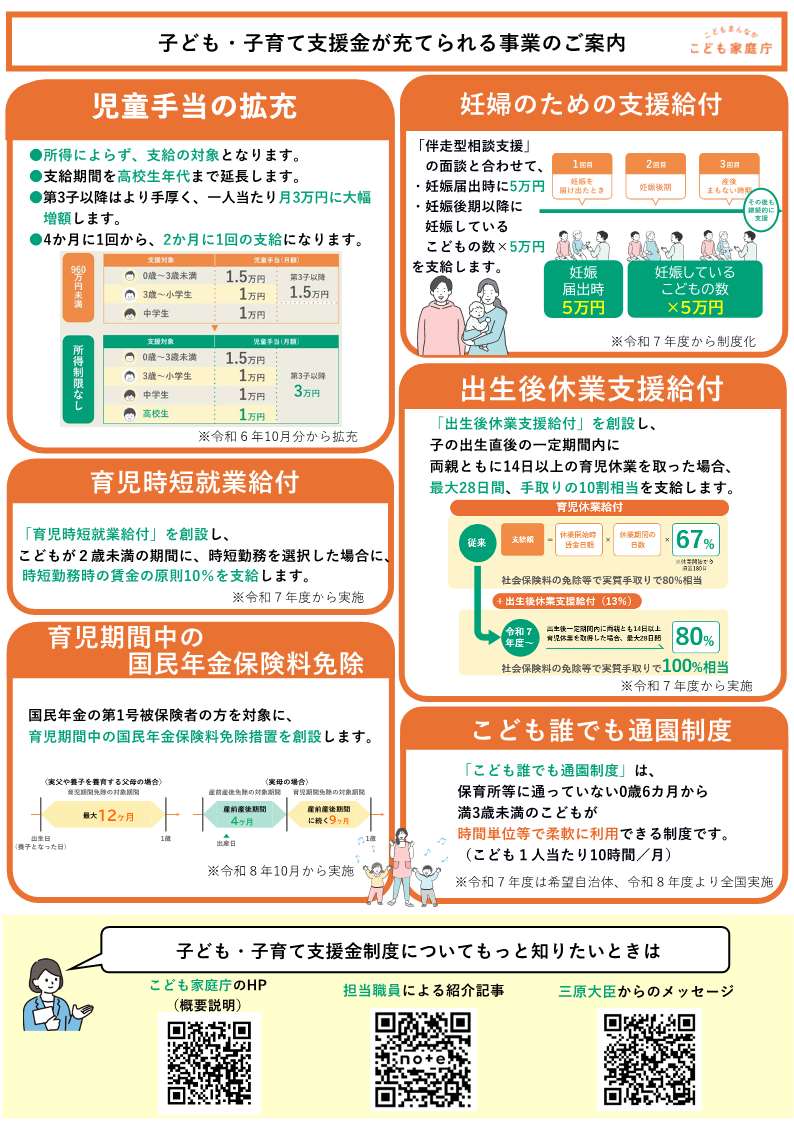
本制度は、児童手当の拡充、妊産婦支援の強化、保育サービスの充実など子育て環境を抜本的に改善するための財源として、医療保険制度の枠組みを通じてすべての国民が能力に応じて公平に拠出するものです。
子ども・子育て支援金の概要等は、以下のリーフレット(PDF:1.74MB)やこども家庭庁ホームページ(外部サイト)をご参照ください。
こども家庭庁ホームページ: https://www.cfa.go.jp/policies/kodomokosodateshienkin
本制度は、児童手当の拡充、妊産婦支援の強化、保育サービスの充実など子育て環境を抜本的に改善するための財源として、医療保険制度の枠組みを通じてすべての国民が能力に応じて公平に拠出するものです。
子ども・子育て支援金の概要等は、以下のリーフレット(PDF:1.74MB)やこども家庭庁ホームページ(外部サイト)をご参照ください。
こども家庭庁ホームページ: https://www.cfa.go.jp/policies/kodomokosodateshienkin
4. Reductions
Reduction for low-income earners
If the income amount of the previous year is less than the following amount, the per capita and household rate will be reduced.
However, in the case of pension income households aged 65 or over, the amount subject to reduction is the amount obtained by deducting 150,000 yen from the previous year's income. In addition, in the case of a fictitious household, the amount of income of the fictitious householder in the previous year is included in the determination of reduction (the number of insured persons in the table below does not include the fictitious householder).
*Active income earners: "Persons with salary income of over 550,000 yen or pension income of over 600,000 yen under the age of 65 and over 1,250,000 yen over the age of 65"
| Standard income amount | Reduction rate (per capita/household) |
| Total household income 430,000 yen + {100,000 yen x (number of active income earners* - 1) or less | 70% reduction |
|---|---|
| Total household income 430,000 yen + (290,000 yen x number of insured persons) + {100,000 yen x (number of active income earners - 1) or less | 50% reduction |
| Total household income 430,000 yen + (535,000 yen x number of insured persons) + {100,000 yen x (number of active income earners - 1) or less | 20% reduction |
Measures to reduce per capita tax for children
In conjunction with the enforcement of the law amending the Health Insurance Act to create a social insurance system that is suitable for all generations, a reduction in the per capita tax for children has been introduced from April 1, 2022.
To reduce economic burden on child-rearing households, the per capita amount for preschool children is reduced by half across the board, regardless of the number of children or income. If a reduction is already being applied under another system, the per capita amount after that reduction will be reduced by half
No application is required to receive this reduction.
Full exemption from per capita tax for children under 18 years of age
As a unique initiative Niseko Town, in order to further reduce the financial burden on child-rearing households, the town is exempting all per capita tax fees for children under the age of 18 as of FY2025.
The exemption applies to all children under the age of 18, regardless of the household's income. If a reduction is already being applied under another system, the full amount of the per capita amount after that reduction will be exempted.
No application is required to receive this exemption.
The exemption applies to all children under the age of 18, regardless of the household's income. If a reduction is already being applied under another system, the full amount of the per capita amount after that reduction will be exempted.
No application is required to receive this exemption.
Reductions for involuntary unemployed
A system to reduce the burden on those who have lost their jobs due to restructuring or bankruptcy was established in fiscal year 2010. Those who fall under the following categories will have their salary income from the previous year calculated as 30/100 from the time of unemployment until the end of the following fiscal year. In order to receive the reduction, you will need to present your "Employment Insurance Eligibility Certificate" at the town hall.
[Eligible people] Unemployment reason code 11, 12, 21, 22, 31, 32 (unemployment reason code for workers with specific qualifications as recipients)
23, 33, 34 (unemployment reason code for workers with specific reasons for leaving their job)
*Those who are 65 years old or older at the time of leaving their job are not eligible.
*Even if you fit the above code, you will not be eligible if you have the "Special Benefit Eligibility Certificate".
Insurance tax exemption system for the prenatal and postnatal period
From January 1, 2020, a system will begin to exempt insured persons who give birth from the National Health Insurance tax.
[Eligible persons and applicable insurance tax]
Income-based and per capita amounts for insured persons whose expected date of birth is November 1, 2023 or later
[Target period]
・In case of single pregnancy
Insurance tax exemption applicable for 4 months from the month before the expected birth month
・In case of multiple pregnancy
Insurance tax exemption applicable for 6 months from 3 months before the expected birth month
*Since the system started in January 2020, periods before that are not eligible for reduction.
| 3 months before | 2 months before | 1 month before | Expected birth month | 1 month after | 2 months after | |
| Single pregnancy | ☆ | ☆ | ☆ | ☆ | ||
|---|---|---|---|---|---|---|
| Multiple pregnancy | ☆ | ☆ | ☆ | ☆ | ☆ | ☆ |
An application is required to receive this exemption.
Please prepare the application form for insurance tax reduction for the prenatal and postnatal period below, along with your maternal and child health handbook, and apply at the Health & Welfare Division counter at the town hall or by mail.
Please prepare the application form for insurance tax reduction for the prenatal and postnatal period below, along with your maternal and child health handbook, and apply at the Health & Welfare Division counter at the town hall or by mail.
Please see the leaflet below for more details.
Niseko Town initiative tax reduction system for the elderly
One half of the tax amount can be reduced if tax inspectors deem the household to be under distress in terms of living or it is considered that the current situation of the household will not support payment in full. The following requirements apply for reductions to be put in place. Please contact the Tax Division for more information.
- Households consisting only of dependent relatives of elderly people aged 75 years or older or those aged 65 or over who have been certified as disabled by the Association of Medical Care for the Elderly
- Households with an expected annual income of 800,000 yen or less (330,000 yen for each insured person)
- Those who have a household deposit savings of less than 1.2 million yen
- Those who do not have other assets (excluding property tax free taxable property and fixed assets necessary for residence)
If you have any questions about whether you are eligible for a reduction or exemption, please contact the Tax Division or the Health & Welfare Division.
You can pay at convenience stores, through smartphone app, or on local tax payment websites.
You can use the NHI tax payment slip to pay at convenience stores nationwide.
However, payment slips for which the payment amount exceeds 300,000 yen, payment slips on which bar codes are not printed, payment slips on which the bar code portions are dirty, etc. can not be handled at convenience stores. Please pay at a financial institution or at the town hall counter.
※ Payment at a convenience store can be handled until the end of May of the following tax year. After that date you will not be able to pay at a convenience store and must pay at the town hall counter or through another financial institution.
In addition, you can pay your taxes from home or anywhere using a smartphone or computer via the smartphone app or local tax payment website. You can also choose the payment method, and you can check your payment status on the app or website.
For more details, please see the link below.
To consider when filing for tax return
Only the national health insurance tax paid from January to December can be recorded as a deduction for social insurance premiums on the tax return. If you pay after January of this year, you will be subject to the next year's tax return. Please be careful when filing your tax return.
5.よくあるお問い合わせ
Q.国民健康保険に加入していない家族の名前で納税通知書が届きましたがなぜですか?
国保税は世帯主に納税義務があるため、世帯主が国保以外の健康保険(社会保険など)に加入していても、ご家族のどなたかが国保に加入していれば国保に加入している方の分で国保税を計算して、世帯主に納税通知書を送付しています。
Q.会社の健康保険に入ったのに、国保税も納めなければならないのですか?
社会保険に加入した場合、加入月以降は社会保険料のみがかかり、国保税は社会保険加入前月までの分がかかります。
ですが、国保税の納期の関係などにより社会保険に加入してからも国保税の支払いが残る場合があります。
また、国保を離脱する手続きをご自身でしていただく必要があります。自動的に切り替わるものではありませんので国保以外の健康保険に加入された方は国保離脱のお手続きをお願いいたします。
手続きをした翌月に再計算し、通知書を送付いたします。
離脱のお手続きの際は下記の物をご用意して役場1階3番窓口までお越しください。
・社会保険の資格確認書、または資格情報のお知らせ
・国民健康保険の保険証または資格確認書(お持ちの場合)
・納税義務者の銀行口座が確認できるもの(通帳またはキャッシュカードなど)
・マイナンバーを確認できるもの
Q.去年より税額が高くなっています。なぜですか?
表面の計算方法のとおり計算しているため、次のいずれかに該当する世帯は国保税が去年度より高くなっている可能性があります。
・国保に新しく加入した方がいる場合
・国保加入者の前年の収入が増えている場合
・国保加入者で40歳になった方がいる場合
・18歳以上で所得の申告をしていない世帯員がいる場合
・軽減判定区分が変更になった場合
上記に該当しない場合でも税額が去年度より高くなる可能性はありますので、詳細についてはご連絡もしくはご来庁ください。
※お電話では本人確認ができないため、答えられる範囲には限度があります。
Q.昨年は収入がありませんでした。所得の申告は必要ですか。
・収入がなくても申告は必ず必要です。
国民健康保険では、所得に応じて、国民健康保険税の算定や高額療養費の自己負担限度額の判定などを行います。
そのため、収入がない場合も、国民健康保険の加入者とその世帯主の方は所得の申告が必ず必要となります。
【国民健康保険税の軽減措置が正しく計算されない場合があります】
加入者と世帯主の中に一人でも申告がない方がいると、軽減割合の判定ができず、国民健康保険税が正しく計算されない場合があります。収入がない世帯も、申告がない状態では軽減措置は適用されません。